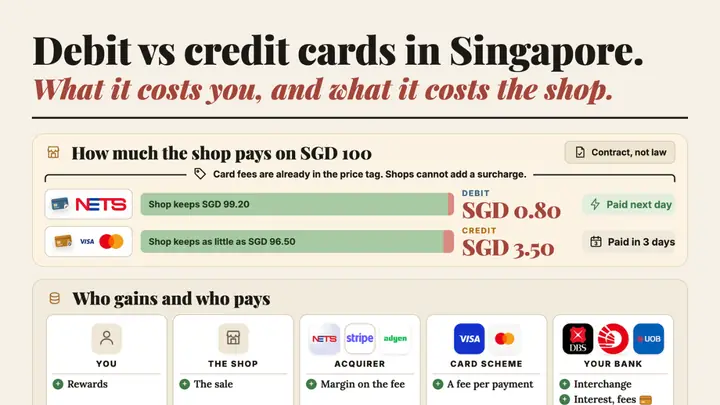
You checked Google before you bought that haul of Kit Kats in Japan to take back to the office, only to find out that your card charged you more. Google shows one SGD rate, your statement shows another, and you're never sure how much the difference will be when tapping. Where did the difference go, and who got it?

The answer sits in the moment you tap. This piece traces where the money goes whenever you tap your card overseas. Once you see who earns from each tap, it also becomes clear why multi-currency cards tend to cost far less than a plain bank card.

  • SGD 27.6B

    Billed on Singapore credit and charge cards in Q2 2026, up 8% on a year earlier

    MAS via SingStat Q2 2026

  • +13%spend

    Cross-border spend in the quarter to June 2026 against a year earlier, in constant dollars

    Visa results Q2 2026

  • +12%spend

    Cross-border spend in the quarter to June 2026 against a year earlier, in local currency

    Mastercard results Q2 2026

  • +37%spend

    Card spend in the year to March 2026 against the year before, to USD 43.6B worldwide

    Wise results FY2026

What each card costs you

On one tap in Japan, banks add a fee on top of the Visa or Mastercard rate. Multi-currency cards convert at their own rate, with little or no fee.

Row Bank cards Multi-currency cards
Logos
Row Debit card Credit card Multi-currency A/C YouTrip Wise Revolut
Fees per SGD 100 Card fee, paid in JPY SGD 3.25 All three banks charge 3.25% on a JPY payment. SGD 3.25 The same 3.25% total, when the charge posts. SGD 0 No FX fee. UOB says no mark-up. SGD 0 No fee. Rate within 0.1 to 0.4% of mid-market. SGD 0.20 A conversion fee of about 0.2% for JPY, no mark-up. SGD 0 to 1 Free on weekdays to SGD 5,000 a month, else 1%.
Cash from an ATM Free each monthFee after thatFee from the first SGD 0 SGD 7 + 3.25% E.g. DBS adds a flat fee to the conversion fee. SGD 0 8%, SGD 15 min E.g. a DBS cash advance, with interest from day one. SGD 0 SGD 5 to 7 No FX fee, but all three banks keep a flat fee. SGD 400 2% Of the amount over SGD 400 a month. SGD 100 1.75% Of the amount over SGD 100 a month. SGD 350 2% Of the amount over SGD 350, or five withdrawals.
Getting the card Delivery and replacement With your account E.g. OCBC charges SGD 20 to replace. Apply at the bank Annual fee varies by card, with waivers. Link to account Needs a multi-currency account with that bank. Free card Replacement and delivery cost SGD 10. Free to order Replacement costs SGD 4. First card free Delivery fee shown before you order.
Topping up How money gets in Nothing to load Draws on your bank account. Pay later High interest if unpaid, e.g. DBS at 27.8% a year. Exchange in app Buy JPY ahead with SGD at the bank's rate. Free by bank Card and Apple Pay are free too. Free by bank Other methods can carry a fee. Free by bank Cards cost 0.30 to 2.08% after the first.
Who sets the rate Who picks the JPY rate Visa or Mastercard From wholesale rates, at authorisation. Visa or Mastercard The same rate, applied to the SGD amount. The bank Its own rate, when you buy the JPY in the app. YouTrip Wholesale rates with global partners. Wise The mid-market rate you see on Google. Revolut Its own rate, from market data.
Where money sits How a balance is protected Deposit insured SDIC insures up to SGD 100,000, not foreign currency. A loan Not a balance. You owe the bank. A bank deposit SDIC insures SGD, not foreign currency deposits. Held on trust A claim on segregated funds if it fails. Kept apart Not used to pay creditors if it fails. Not a bank. Held on trust Trust accounts only, no deposit insurance.

Expand to read every figure.

  • In your favour
  • A cost to you
  • Neutral

Who converts the JPY, and who takes a cut?

The shop, the card scheme, your bank or a wallet app can each convert the JPY, and whoever does earns the margin.

1Tap and request2Issuer answers3Clearing4Settlement5After

ATypical bank debit card, paid in the local currency

1 The tap and the request The scheme converts at the request, so the issuer is asked in SGD. Taps to pay JPY 10,000 Can this card pay JPY 10,000? Converts to SGD, rate fixed now Request with SGD equivalent 2 The issuer answers The issuer holds an SGD amount and converts nothing itself. Checks the SGD amount and fraud, holds it Approved in SGD Approved, JPY 10,000 3 Sales are batched and cleared The scheme reuses the authorisation rate. Fees come on top at posting. Batches the day's sales Clearing records in JPY Applies the rate fixed at authorisation Sale data with SGD equivalent Posts the SGD amount plus fees 4 Money settles and the merchant is paid Banks settle in their own currencies, SGD and JPY here, and the merchant is paid in JPY. Pays net, in SGD Pays net, in JPY Merchant is paid in JPY 5 After the payment A refund converts at a new rate. A lost chargeback carries any rate move. Hold becomes a charge in SGD Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Earns Pays RewardsOn some cardsThe JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cut1.00% fee on the SGDamountCharged by the schemeInterchangeLargest cut2.25% fee on the SGDamountThe bank's part of the3.25%The JPY 10,000 price3.25% in fees on the SGDamountOn top of the scheme rateMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkRewardsFraud losses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer DBS, OCBC, UOB

Expand to read the labels.

What to know

Typical bank debit card, paid in the local currency

Visa or Mastercard converts the JPY to SGD at the tap, at its own rate. The bank holds an SGD amount and adds 3.25% in fees on top.

What it costs
Total
3.25% of the SGD amount, on top of the scheme's rate, at DBS, OCBC and UOB
Card scheme
1.00% to Visa or Mastercard, per DBS and OCBC
Bank
2.25% at DBS and OCBC. UOB states 3.25% without a split
If the shop converts
2.8% at DBS, plus the shop's margin, see flow B
Who converts Visa or MastercardAt the tapIts own rate
The full comparison Compare every card

Key facts

  • The amount comes straight out of your account in SGD. DBS deducts it directly, and the card must be enabled for overseas use first.
  • DBS says the rate comes from wholesale interbank or government-mandated rates. DBS, OCBC and UOB all say a currency other than USD is converted into USD first and then into SGD.
  • Visa says its system applies the rate available at authorisation for clearing and settlement, and Mastercard says its rates are specific to the date and time the bank authorises the payment.
  • Visa lets an issuer add a percentage to its rate and requires the issuer to disclose it. HSBC shows 1.5% of its own plus up to 1% from Visa.

Not in the public record The gap between the scheme rate and a mid-market rate is not stated. Nor is when UOB converts a foreign-currency hold, or how long a debit hold lasts before the merchant's claim posts.

Notes on the earns and pays rows

The parties and the order of the cuts follow the card payments piece. Industry practice, and no market's split is quoted. The percentages are DBS fees on the SGD amount, from its foreign transaction fee guide, which gives the same split for debit and credit cards. They are fees and not a second conversion. OCBC's debit fee schedule gives the same 1 percent and 2.25 percent split, and UOB's debit agreement states 3.25 percent as one figure. A debit card has no credit line, so the issuer carries no credit losses and earns no card interest.

Not stated (4)
Sources (12) DBS, overseas card transaction fees guide (credit and debit, undated), read 15 Oct 2026DBS, card rates and fees (credit section undated, debit section as at 30 Dec 2020), read 14 Oct 2026DBS, important notes on the DBS and POSB debit card (PDF, created 11 Jun 2026), read 15 Oct 2026DBS, transact and withdraw in foreign currency overseas (enable the card for overseas use), read 15 Oct 2026OCBC, OCBC Debit Card (fees and overseas use, undated), read 15 Oct 2026OCBC, fees and charges for debit cards (PDF, rates from 16 Jan 2019), read 15 Oct 2026UOB, debit cardmember agreement (PDF, created 1 Sep 2026), read 15 Oct 2026HSBC Singapore, foreign transaction fee when using your card abroad, read 15 Oct 2026Visa, exchange rate calculator and note on which rate applies (US page, saved copy), read 14 Oct 2026Mastercard, currency converter and note on which rate applies (Singapore), read 14 Oct 2026Visa Core Rules and Visa Product and Service Rules, public edition (18 Apr 2026), sections 1.4.3.2, 1.4.4.5, 4.19, 5.8.9, 5.9.2.3 and 11.4.2, read 13 Oct 2026Mastercard Rules (2 June 2026), rule 6.2, read 13 Oct 2026

BBank debit card, accepting the terminal offer (DCC)

1 The tap and the request Differs from typical card The acquirer quotes an SGD price at its own rate, and the request goes out in SGD. The offer is barred on small contactless taps. Taps to pay JPY 10,000 Asks for an SGD price Sets an SGD price, its own rate and margin SGD price and rate Offers JPY or SGD Chooses SGD Can this card pay SGD? 2 The issuer answers Differs from typical card The request was in SGD, so the scheme only passes it on to the Singapore issuer. Checks the SGD amount and fraud, holds it Approved 3 Sales are batched and cleared Differs from typical card The clearing record is in SGD, so the scheme has nothing to convert. Batches the day's sales Clearing records in SGD Sale data in SGD Posts SGD plus the DCC fee 4 Money settles and the merchant is paid Differs from typical card The scheme converts only to settle the acquirer in its own currency. The acquirer pays the merchant in JPY and can share the margin. Pays net, in SGD Converts to JPY only to settle the acquirer Pays net, in JPY Merchant is paid in JPY 5 After the payment Differs from typical card A DCC refund goes back at the original amount or rate, not converted afresh. Hold becomes a charge in SGD Later, a refund in SGD Credits the same SGD amount Earns Pays RewardsOn some cardsThe JPY 10,000 saleA share of the DCCmarginRate unknownMargin on the merchantfeeMiddle cutA margin in the DCC rateSet by the acquirer or itsproviderA fee per paymentSmallest cut1.00% fee on the SGDamountCharged by the schemeInterchangeLargest cutThe bank's part of the2.8%1.80% at DBSThe JPY 10,000 priceConverted to SGD by theacquirer2.8% in fees plus amargin in the rateMargin size unknownMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkRewardsFraud losses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer DBS, OCBC, UOB 1 The tap and the request Differs from typical card The acquirer quotes an SGD price at its own rate, and the request goes out in SGD. The offer is barred on small contactless taps. Typical cardThis flow Taps to pay JPY 10,000 Can this card pay JPY 10,000? Converts to SGD, rate fixed now Request with SGD equivalent Taps to pay JPY 10,000 Asks for an SGD price Sets an SGD price, its own rate and margin SGD price and rate Offers JPY or SGD Chooses SGD Can this card pay SGD? 2 The issuer answers Differs from typical card The request was in SGD, so the scheme only passes it on to the Singapore issuer. Typical cardThis flow Checks the SGD amount and fraud, holds it Approved in SGD Approved, JPY 10,000 Checks the SGD amount and fraud, holds it Approved 3 Sales are batched and cleared Differs from typical card The clearing record is in SGD, so the scheme has nothing to convert. Typical cardThis flow Batches the day's sales Clearing records in JPY Applies the rate fixed at authorisation Sale data with SGD equivalent Posts the SGD amount plus fees Batches the day's sales Clearing records in SGD Sale data in SGD Posts SGD plus the DCC fee 4 Money settles and the merchant is paid Differs from typical card The scheme converts only to settle the acquirer in its own currency. The acquirer pays the merchant in JPY and can share the margin. Typical cardThis flow Pays net, in SGD Pays net, in JPY Merchant is paid in JPY Pays net, in SGD Converts to JPY only to settle the acquirer Pays net, in JPY Merchant is paid in JPY 5 After the payment Differs from typical card A DCC refund goes back at the original amount or rate, not converted afresh. Typical cardThis flow Hold becomes a charge in SGD Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Hold becomes a charge in SGD Later, a refund in SGD Credits the same SGD amount Earns Pays RewardsOn some cardsThe JPY 10,000 saleA share of the DCCmarginRate unknownMargin on the merchantfeeMiddle cutA margin in the DCC rateSet by the acquirer or itsproviderA fee per paymentSmallest cut1.00% fee on the SGDamountCharged by the schemeInterchangeLargest cutThe bank's part of the2.8%1.80% at DBSThe JPY 10,000 priceConverted to SGD by theacquirer2.8% in fees plus amargin in the rateMargin size unknownMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkRewardsFraud losses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer DBS, OCBC, UOB

Expand to read the labels.

What to know

Bank debit card, accepting the terminal offer (DCC)

The shop's bank or a DCC provider converts at the tap, at the rate it offers and with its own margin. Visa or Mastercard converts nothing for you.

What it costs
Bank fees
2.8% on a debit card at DBS, OCBC and UOB, plus the margin in the shop's rate
Split at DBS
1.00% + 1.80% to the scheme and to the bank, per DBS's guide
Credit card at DBS
1.00% the scheme's fee only, with no bank fee
Paying in JPY instead
3.25% whether the offer costs more depends on the margin, which no source gives
Who converts Shop's bank or DCC providerAt the tapIts own margin
The full comparison Compare every card

Key facts

  • The amount still comes straight out of your account in SGD. Accepting the offer changes only the currency of the charge.
  • Mastercard says you are debited at the acquirer's rate, and that a markup is a commercial agreement between the acquirer and the shop. DBS says the rate can differ from prevailing rates.
  • The request and the clearing record are in SGD, with the JPY amount carried as information. The scheme converts only when it settles the acquirer in its own currency.
  • Visa requires the shop to say the offer is optional, not to pre-select it and to get express agreement. The receipt must show the rate and any margin over a wholesale rate.
  • Mastercard says DCC is not its product, and that its rates do not apply when the shop converts.

Not in the public record The size of the margin, how it splits between the shop, its bank and a DCC provider, and how often terminals offer DCC are not stated.

Notes on the earns and pays rows

The parties and the order of the cuts follow the card payments piece. Industry practice, and no market's split is quoted. How the DCC margin splits between the merchant, the acquirer and a DCC provider is not published, apart from the Adyen statement. The DBS figures are its debit card fees. On its credit card DBS charges no bank fee on a DCC payment. Parties without an entry have no reported change from the typical card.

Not stated (4)
Sources (9) DBS, overseas card transaction fees guide (credit and debit, undated), read 15 Oct 2026DBS, card rates and fees (credit section undated, debit section as at 30 Dec 2020), read 14 Oct 2026OCBC, fees and charges for debit cards (PDF, rates from 16 Jan 2019), read 15 Oct 2026UOB, debit cardmember agreement (PDF, created 1 Sep 2026), read 15 Oct 2026Visa Core Rules and Visa Product and Service Rules, public edition (18 Apr 2026), sections 1.4.3.2, 1.4.4.5, 4.19, 5.8.9, 5.9.2.3 and 11.4.2, read 13 Oct 2026Mastercard, currency converter and note on which rate applies (Singapore), read 14 Oct 2026Mastercard, Dynamic Currency Conversion Performance Guide, merchant version (2025), sections 2.1, 2.5.3 and 2.6, read 14 Oct 2026Adyen, dynamic currency conversion on terminals, read 14 Oct 2026Adyen, what currencies are available for payouts, read 14 Oct 2026

CBank credit card, paid in the local currency

1 The tap and the request Same as typical card Taps to pay JPY 10,000 Can this card pay JPY 10,000? Converts to SGD, rate fixed now Request with SGD equivalent 2 The issuer answers Differs from typical card The issuer checks a credit line and not a balance, and holds SGD against the limit. Checks the credit limit and fraud, holds SGD Approved in SGD Approved, JPY 10,000 3 Sales are batched and cleared Same as typical card Batches the day's sales Clearing records in JPY Applies the rate fixed at authorisation Sale data with SGD equivalent Posts the SGD amount plus fees 4 Money settles and the merchant is paid Same as typical card Pays net, in SGD Pays net, in JPY Merchant is paid in JPY 5 After the payment Differs from typical card The charge goes on a statement and is paid by the due date. Interest runs if it is not paid in full. Hold becomes a charge on the statement Statement in SGD, with a due date Pays the bill by the due date Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Earns Pays RewardsOn some cardsThe JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cut1.00% fee on the SGDamountCharged by the schemeInterchangeLargest cut2.25% fee on the SGDamountThe bank's own part of the3.25%Card interest and feesIf not paid in fullThe JPY 10,000 price3.25% in fees on the SGDamountOn top of the scheme rateInterest if not paid infullMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkRewardsFraud lossesCredit lossesThe bank lends until thebill is paid Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer DBS, OCBC, UOB 1 The tap and the request Same as typical card Taps to pay JPY 10,000 Can this card pay JPY 10,000? Converts to SGD, rate fixed now Request with SGD equivalent 2 The issuer answers Differs from typical card The issuer checks a credit line and not a balance, and holds SGD against the limit. Typical cardThis flow Checks the SGD amount and fraud, holds it Approved in SGD Approved, JPY 10,000 Checks the credit limit and fraud, holds SGD Approved in SGD Approved, JPY 10,000 3 Sales are batched and cleared Same as typical card Batches the day's sales Clearing records in JPY Applies the rate fixed at authorisation Sale data with SGD equivalent Posts the SGD amount plus fees 4 Money settles and the merchant is paid Same as typical card Pays net, in SGD Pays net, in JPY Merchant is paid in JPY 5 After the payment Differs from typical card The charge goes on a statement and is paid by the due date. Interest runs if it is not paid in full. Typical cardThis flow Hold becomes a charge in SGD Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Hold becomes a charge on the statement Statement in SGD, with a due date Pays the bill by the due date Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Earns Pays RewardsOn some cardsThe JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cut1.00% fee on the SGDamountCharged by the schemeInterchangeLargest cut2.25% fee on the SGDamountThe bank's own part of the3.25%Card interest and feesIf not paid in fullThe JPY 10,000 price3.25% in fees on the SGDamountOn top of the scheme rateInterest if not paid infullMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkRewardsFraud lossesCredit lossesThe bank lends until thebill is paid Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer DBS, OCBC, UOB

Expand to read the labels.

What to know

Bank credit card, paid in the local currency

Visa or Mastercard converts at the tap, as on a debit card. The charge goes on your statement with 3.25% in fees on top, and interest can run if the balance is not paid in full.

What it costs
Total
3.25% of the SGD amount, on top of the scheme's rate, applied at processing
Card scheme
1.00% to Visa or Mastercard
Bank
2.25% at DBS
If the shop converts
1.00% at DBS, the bank fee is nil and the scheme's fee remains
When you pay
Interest
If unpaid runs from the transaction date, for example at DBS
Who converts Visa or MastercardAt the tapIts own rate
The full comparison Compare every card

Key facts

  • The bank's credit line, billed in SGD. Interest can run from the transaction date if the balance is not paid in full by the due date, for example at DBS.
  • DBS says its 1.00% and 2.25% are fees and not a second conversion. Its credit table is undated.
  • Other banks charge about the same. OCBC states 1% plus 2.25%, Standard Chartered 1% plus 2.5%, Citibank up to 3.25%, and UOB 3.25% with 1% kept by Visa.
  • A card marked 0% FX fees waives the administrative fee only, UOB's EVOL card says, and the rate the scheme applies is unchanged.
  • Mastercard's rules and Visa's require the issuer to disclose any conversion charge or fee it adds.

Not in the public record What the bank fee pays for is not stated. DBS calls it an administrative fee, and no bank page gives a breakdown of its part.

Notes on the earns and pays rows

The parties and the order of the cuts follow the card payments piece. Industry practice, and no market's split is quoted. The percentages are DBS credit card fees on the SGD amount, and they are fees and not a second conversion. The credit card adds a credit line, so the issuer earns card interest and carries credit losses, which a debit card does not. Parties without an entry have no reported change from the typical card.

Not stated (2)
Sources (11) DBS, card rates and fees (credit section undated, debit section as at 30 Dec 2020), read 14 Oct 2026DBS, overseas card transaction fees guide (credit and debit, undated), read 15 Oct 2026Visa Core Rules and Visa Product and Service Rules, public edition (18 Apr 2026), sections 1.4.3.2, 1.4.4.5, 4.19, 5.8.9, 5.9.2.3 and 11.4.2, read 13 Oct 2026Mastercard Rules (2 June 2026), rule 6.2, read 13 Oct 2026OCBC, credit card help, foreign currency transactions (from 3 Dec 2019), read 15 Oct 2026Standard Chartered Singapore, pricing guide (credit card foreign currency transactions, undated), read 15 Oct 2026Citibank Singapore, banking fees and credit card charges (foreign currency section undated), read 15 Oct 2026UOB, general information on UOB credit cards (PDF, updated 23 Jul 2025), read 15 Oct 2026HSBC Singapore, foreign transaction fee when using your card abroad, read 15 Oct 2026UOB, EVOL card (0% FX fees, with its definition of FX fees), read 15 Oct 2026MAS, response on international fees on credit card transactions (8 December 2015), read 15 Oct 2026

DBank debit card with a multi-currency account

0 Before the tap Differs from typical card The conversion happens here, at the bank's rate, long before the tap. Exchanges SGD for JPY in the app Holds JPY at its own rate 1 The tap and the request Differs from typical card The request goes straight to the issuer in JPY, so no conversion is drawn. Taps to pay JPY 10,000 Can this card pay JPY 10,000? 2 The issuer answers Differs from typical card The payment comes from the JPY balance. If it is short, the bank charges the SGD account instead, and the fee depends on the bank. Checks and debits the JPY balance Approved 3 Sales are batched and cleared Differs from typical card Nothing converts, since the JPY was already held. Batches the day's sales Sales in JPY sent on 4 Money settles and the merchant is paid Differs from typical card Settlement is in JPY as well, and the merchant is paid in JPY. Pays net, in JPY Pays net, in JPY Merchant is paid in JPY 5 After the payment Not stated No bank page says how a refund is credited. Hold becomes a charge in JPY Later, a refund in JPY Earns Pays RewardsOn some cardsThe JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cutInterchangeLargest cutMargin in its exchangerateUOB says noneThe JPY 10,000 priceNo FX fee on the cardThe JPY was already heldMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkRewardsFraud losses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer DBS, OCBC, UOB 0 Before the tap Differs from typical card The conversion happens here, at the bank's rate, long before the tap. Typical cardNo messages at this stepThis flow Exchanges SGD for JPY in the app Holds JPY at its own rate 1 The tap and the request Differs from typical card The request goes straight to the issuer in JPY, so no conversion is drawn. Typical cardThis flow Taps to pay JPY 10,000 Can this card pay JPY 10,000? Converts to SGD, rate fixed now Request with SGD equivalent Taps to pay JPY 10,000 Can this card pay JPY 10,000? 2 The issuer answers Differs from typical card The payment comes from the JPY balance. If it is short, the bank charges the SGD account instead, and the fee depends on the bank. Typical cardThis flow Checks the SGD amount and fraud, holds it Approved in SGD Approved, JPY 10,000 Checks and debits the JPY balance Approved 3 Sales are batched and cleared Differs from typical card Nothing converts, since the JPY was already held. Typical cardThis flow Batches the day's sales Clearing records in JPY Applies the rate fixed at authorisation Sale data with SGD equivalent Posts the SGD amount plus fees Batches the day's sales Sales in JPY sent on 4 Money settles and the merchant is paid Differs from typical card Settlement is in JPY as well, and the merchant is paid in JPY. Typical cardThis flow Pays net, in SGD Pays net, in JPY Merchant is paid in JPY Pays net, in JPY Pays net, in JPY Merchant is paid in JPY 5 After the payment Not stated No bank page says how a refund is credited. Typical cardThis flow Hold becomes a charge in SGD Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Hold becomes a charge in JPY Later, a refund in JPY Earns Pays RewardsOn some cardsThe JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cutInterchangeLargest cutMargin in its exchangerateUOB says noneThe JPY 10,000 priceNo FX fee on the cardThe JPY was already heldMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkRewardsFraud losses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer DBS, OCBC, UOB

Expand to read the labels.

What to know

Bank debit card with a multi-currency account

Nothing converts at the tap. You bought the JPY earlier in the bank's app, at the bank's own rate, and the card spends that balance with no FX fee.

What it costs
DBS
0% zero FX conversion fees, also at overseas ATMs
OCBC
0% no foreign currency transaction fee, and no admin fee at ATMs when the balance covers it
UOB
0% 0% FX fees, and the 2.5% ATM admin fee is waived when the balance covers it
Where it sits
The JPY rate the bank's own rate when you bought the JPY
Who converts You, in the bank appBefore the tripBank's own rate
The full comparison Compare every card

Key facts

  • DBS My Account holds 12 currencies and the card spends 11, JPY included. OCBC's Global Savings Account holds up to 10 and the card spends 9. UOB FX+ holds 10, as an add-on to a UOB One Account.
  • The card must be linked. DBS says in the app, and OCBC says a card links to one Global Savings Account. All three leave CNH out of card spending.
  • If the JPY balance is short, no page says the payment is declined. The bank charges the SGD account instead. At OCBC the usual 3.25% on a debit card then applies, and DBS says only that the waiver needs enough balance.
  • At an overseas ATM, DBS's rate table gives SGD 7 a withdrawal, OCBC's fee schedule 3% with a SGD 5 minimum and SGD 20 maximum, and UOB a flat SGD 5 at non-UOB ATMs. The ATM owner may add a fee.
  • Visa describes this design for its own multi-currency cards. An issuer may convert at the time of purchase when the foreign balance is short, and must disclose the rate and the alternative account debited (rule 4.19).

Not in the public record The rate each bank sells JPY at, the fee when the balance is short on a purchase, and how a refund is credited are not stated.

Notes on the earns and pays rows

The parties and the order of the cuts follow the card payments piece. Industry practice, and no market's split is quoted. The wording is each bank's own. DBS, OCBC and UOB each waive the card's FX fee when the card draws on a JPY balance held at the bank. DBS and OCBC describe their exchange rates as attractive or real-time, and UOB says its conversion has no mark-up. None gives a figure. Parties without an entry have no reported change from the typical card.

Not stated (4)
Sources (12) DBS, My Account (12 foreign currencies, card use, FAQ on funds), read 17 Oct 2026DBS, Visa Debit Card (zero FX fees on 11 currencies when linked to My Account), read 17 Oct 2026OCBC, Global Savings Account (9 card currencies, linked debit card, FAQ), read 17 Oct 2026UOB, FX+ account and FX+ Debit Card, read 17 Oct 2026DBS, card rates and fees (credit section undated, debit section as at 30 Dec 2020), read 14 Oct 2026DBS, transact and withdraw in foreign currency overseas (enable the card for overseas use), read 15 Oct 2026OCBC, OCBC Debit Card (fees and overseas use, undated), read 15 Oct 2026OCBC, fees and charges for debit cards (PDF, rates from 16 Jan 2019), read 15 Oct 2026Visa Core Rules and Visa Product and Service Rules, public edition (18 Apr 2026), sections 1.4.3.2, 1.4.4.5, 4.19, 5.8.9, 5.9.2.3 and 11.4.2, read 13 Oct 2026Visa, exchange rate calculator and note on which rate applies (US page, saved copy), read 14 Oct 2026Mastercard, currency converter and note on which rate applies (Singapore), read 14 Oct 2026SDIC, scope of deposit insurance coverage, read 17 Oct 2026

EMulti-currency card, the JPY balance holds enough

0 Before the tap Differs from typical card The cardholder tops up in SGD, then chooses to exchange it in the app. The provider sets the rate, long before the tap. Tops up SGD in the app Chooses to exchange SGD for JPY Sets the rate, exchanges to JPY JPY balance credited 1 The tap and the request Differs from typical card The request goes straight to the issuer in JPY, so no conversion is drawn. Taps to pay JPY 10,000 Can this card pay JPY 10,000? 2 The issuer answers Differs from typical card The payment comes from the JPY balance. Checks and debits the JPY balance Approved 3 Sales are batched and cleared Differs from typical card Nothing converts, since the JPY was already held. Batches the day's sales Sales in JPY sent on 4 Money settles and the merchant is paid Differs from typical card Settlement is in JPY as well, and the merchant is paid in JPY. Pays net, in JPY Pays net, in JPY Merchant is paid in JPY 5 After the payment Not stated Wise credits a refund in JPY. For the others it is unknown. Hold becomes a charge in JPY Later, a refund in JPY Earns Pays The JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cutA share of the merchantfeeRate unknownThe JPY 10,000 priceNothing to convertThe JPY was already heldMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkFraud and chargebacklosses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer YouTrip, Wise, Revolut 0 Before the tap Differs from typical card The cardholder tops up in SGD, then chooses to exchange it in the app. The provider sets the rate, long before the tap. Typical cardNo messages at this stepThis flow Tops up SGD in the app Chooses to exchange SGD for JPY Sets the rate, exchanges to JPY JPY balance credited 1 The tap and the request Differs from typical card The request goes straight to the issuer in JPY, so no conversion is drawn. Typical cardThis flow Taps to pay JPY 10,000 Can this card pay JPY 10,000? Converts to SGD, rate fixed now Request with SGD equivalent Taps to pay JPY 10,000 Can this card pay JPY 10,000? 2 The issuer answers Differs from typical card The payment comes from the JPY balance. Typical cardThis flow Checks the SGD amount and fraud, holds it Approved in SGD Approved, JPY 10,000 Checks and debits the JPY balance Approved 3 Sales are batched and cleared Differs from typical card Nothing converts, since the JPY was already held. Typical cardThis flow Batches the day's sales Clearing records in JPY Applies the rate fixed at authorisation Sale data with SGD equivalent Posts the SGD amount plus fees Batches the day's sales Sales in JPY sent on 4 Money settles and the merchant is paid Differs from typical card Settlement is in JPY as well, and the merchant is paid in JPY. Typical cardThis flow Pays net, in SGD Pays net, in JPY Merchant is paid in JPY Pays net, in JPY Pays net, in JPY Merchant is paid in JPY 5 After the payment Not stated Wise credits a refund in JPY. For the others it is unknown. Typical cardThis flow Hold becomes a charge in SGD Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Hold becomes a charge in JPY Later, a refund in JPY Earns Pays The JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cutA share of the merchantfeeRate unknownThe JPY 10,000 priceNothing to convertThe JPY was already heldMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkFraud and chargebacklosses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer YouTrip, Wise, Revolut

Expand to read the labels.

What to know

Multi-currency card, the JPY balance holds enough

Nothing converts at the tap. You exchanged SGD for JPY earlier in the app, at the provider's own rate, and the card spends that balance.

What it costs
Where it sits
At the exchange what the JPY cost when you bought it
Who converts You, in the appBefore the tripProvider's own rate
The full comparison Compare every card

Key facts

Not in the public record Which of Visa or Mastercard a Wise or Revolut card runs on, what each earns from the shop, and which currency a refund comes back in are not stated.

Notes on the earns and pays rows

The parties and the order of the cuts follow the card payments piece. Industry practice, and no market's split is quoted. The wording is each provider's own. YouTrip describes its rates as typically within a marginal 0.1 percent of published rates. YouTrip says it earns a small commission from the merchant through Mastercard, Wise's UK blog says part of its revenue is interchange, and Revolut's pages say nothing on it. None gives a rate. The Singapore Wise supplement names Wise Asia-Pacific Pte Ltd as its issuer. Parties without an entry have no reported change from the typical card.

Not stated (5)
Sources (33) YouTrip Singapore, general terms and conditions (page undated), read 13 Oct 2026YouTrip help, why does my exchange rate change after my transaction, read 13 Oct 2026YouTrip help, which currency wallet will be deducted for overseas transactions, read 13 Oct 2026YouTrip help, what is SmartExchange, read 13 Oct 2026YouTrip help, how YouTrip makes money, read 13 Oct 2026YouTrip help, what are wholesale exchange rates, read 14 Oct 2026MAS Financial Institutions Directory, You Technologies Group (Singapore) Pte. Ltd., read 14 Oct 2026Wise, Card Supplement to the Customer Agreement for Singapore (last updated 16 Feb 2026), read 13 Oct 2026Wise help, what if I spend money in a currency I do not have in my account, read 13 Oct 2026Wise help, what are the Wise card fees, read 13 Oct 2026Wise, card fees for Singapore, with its calculator (page undated), read 14 Oct 2026MAS Financial Institutions Directory, Wise Asia-Pacific Pte. Ltd., read 14 Oct 2026Revolut Singapore, personal fees (Standard plan, undated page), read 15 Oct 2026Revolut Singapore help, problems with a refund, read 15 Oct 2026Revolut UK blog, using Revolut abroad (16 Jan 2026), on weekday and weekend rates, read 15 Oct 2026Revolut Singapore, cardholder terms (undated page), read 15 Oct 2026Revolut Singapore help, what currency will I be charged in, read 15 Oct 2026Revolut Singapore help, fees for card payments in a foreign currency, read 15 Oct 2026Revolut Singapore help, what exchange rates does Revolut offer, read 15 Oct 2026Revolut Singapore help, what currencies are supported for spending, read 15 Oct 2026Revolut Japan blog, how to exchange currencies with Revolut (22 Apr 2025), read 15 Oct 2026YouTrip help, why the original transaction amount changed from when I first split it, read 14 Oct 2026YouTrip help, what is Dynamic Currency Conversion (DCC), read 14 Oct 2026YouTrip help, what to do if a refund is not reflected, read 14 Oct 2026Wise Singapore blog, Wise card Singapore review, read 14 Oct 2026Wise UK blog, business card cashback (on how Wise earns from card use), read 14 Oct 2026Wise Platform, relayed authorisation (documentation for card issuers that partner with Wise), read 14 Oct 2026Wise Platform documentation for card issuers, balance currencies (partner guide, not the Singapore card), read 14 Oct 2026Mastercard Rules (2 June 2026), rule 6.2, read 13 Oct 2026Mastercard, Dynamic Currency Conversion Performance Guide, merchant version (2025), sections 2.1, 2.5.3 and 2.6, read 14 Oct 2026Visa, exchange rate calculator and note on which rate applies (US page, saved copy), read 14 Oct 2026Mastercard, currency converter and note on which rate applies (Singapore), read 14 Oct 2026Wise help, how can I receive money to my Wise card (includes refunds), read 15 Oct 2026

FMulti-currency card, the JPY balance is empty or not held

0 Before the tap Differs from typical card Only SGD is loaded, so there is no JPY to spend yet. Tops up SGD in the app Holds SGD, no JPY 1 The tap and the request Differs from typical card The request goes straight to the issuer in JPY. Taps to pay JPY 10,000 Can this card pay JPY 10,000? 2 The issuer answers Differs from typical card With too little JPY, the issuer holds another balance and exchanges it. Insufficient JPY Holds another balance, such as SGD Exchanges it to JPY automatically Applies its own rate Approved 3 Sales are batched and cleared Differs from typical card The final amount can move slightly after the tap. Batches the day's sales Sales in JPY sent on 4 Money settles and the merchant is paid Differs from typical card Settlement is in JPY, and the merchant is paid in JPY. Pays net, in JPY Pays net, in JPY Merchant is paid in JPY 5 After the payment Not stated Wise credits a refund in JPY. For the others it is unknown. Hold becomes a charge Later, a refund in JPY Earns Pays The JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cutExchange feesWise and RevolutA share of the merchantfeeRate unknownThe JPY 10,000 price0% to about 1% inexchange feesOn the amount exchanged,depending on the providerMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkFraud and chargebacklosses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer YouTrip, Wise, Revolut 0 Before the tap Differs from typical card Only SGD is loaded, so there is no JPY to spend yet. Typical cardNo messages at this stepThis flow Tops up SGD in the app Holds SGD, no JPY 1 The tap and the request Differs from typical card The request goes straight to the issuer in JPY. Typical cardThis flow Taps to pay JPY 10,000 Can this card pay JPY 10,000? Converts to SGD, rate fixed now Request with SGD equivalent Taps to pay JPY 10,000 Can this card pay JPY 10,000? 2 The issuer answers Differs from typical card With too little JPY, the issuer holds another balance and exchanges it. Typical cardThis flow Checks the SGD amount and fraud, holds it Approved in SGD Approved, JPY 10,000 Insufficient JPY Holds another balance, such as SGD Exchanges it to JPY automatically Applies its own rate Approved 3 Sales are batched and cleared Differs from typical card The final amount can move slightly after the tap. Typical cardThis flow Batches the day's sales Clearing records in JPY Applies the rate fixed at authorisation Sale data with SGD equivalent Posts the SGD amount plus fees Batches the day's sales Sales in JPY sent on 4 Money settles and the merchant is paid Differs from typical card Settlement is in JPY, and the merchant is paid in JPY. Typical cardThis flow Pays net, in SGD Pays net, in JPY Merchant is paid in JPY Pays net, in JPY Pays net, in JPY Merchant is paid in JPY 5 After the payment Not stated Wise credits a refund in JPY. For the others it is unknown. Typical cardThis flow Hold becomes a charge in SGD Later, a refund of JPY 10,000 Converts at a new rate Refund, SGD equivalent Credits SGD at the new rate Hold becomes a charge Later, a refund in JPY Earns Pays The JPY 10,000 saleMargin on the merchantfeeMiddle cutA fee per paymentSmallest cutExchange feesWise and RevolutA share of the merchantfeeRate unknownThe JPY 10,000 price0% to about 1% inexchange feesOn the amount exchanged,depending on the providerMerchant feeA share of each saleTerminal or gateway feeInterchange to theissuerScheme feesChargeback lossesIf the merchant can'trepay, and any rate moveRunning the networkFraud and chargebacklosses Cardholder Merchant Acquirer The shop's bank orprovider Card scheme Issuer YouTrip, Wise, Revolut

Expand to read the labels.

What to know

Multi-currency card, the JPY balance is empty or not held

The card's provider converts at the tap, at its own rate, from another balance such as SGD. You do nothing, and the cost runs from 0% to about 1%.

What it costs
YouTrip
0% no fee or markup, with a rate typically within 0.1% of published rates
Wise
About 0.2% a conversion fee on the mid-market rate, SGD 1.98 on SGD 1,000 to JPY on an undated calculator
Revolut
0% to 1% free on weekdays within SGD 5,000 a month on Standard, then 1%, and 1% at weekends
Who converts The card's providerAt the tapIts own rate
The full comparison Compare every card

Key facts

Not in the public record When Wise prices the exchange, when YouTrip fixes the final rate, the size of Revolut's spread, and which currency a refund comes back in are not stated.

Notes on the earns and pays rows

The parties and the order of the cuts follow the card payments piece. Industry practice, and no market's split is quoted. The wording is each provider's own. Wise's Singapore calculator showed SGD 1.98 on SGD 1,000 converted to JPY, and its fee page is undated. Revolut's help page charges nothing on a weekday within a monthly allowance and 1 percent on a Standard plan weekend exchange. Parties without an entry have no reported change from the typical card.

Not stated (7)
Sources (37) YouTrip Singapore, general terms and conditions (page undated), read 13 Oct 2026YouTrip help, why does my exchange rate change after my transaction, read 13 Oct 2026YouTrip help, which currency wallet will be deducted for overseas transactions, read 13 Oct 2026YouTrip help, what is SmartExchange, read 13 Oct 2026YouTrip help, how YouTrip makes money, read 13 Oct 2026YouTrip help, what are wholesale exchange rates, read 14 Oct 2026MAS Financial Institutions Directory, You Technologies Group (Singapore) Pte. Ltd., read 14 Oct 2026Wise, Card Supplement to the Customer Agreement for Singapore (last updated 16 Feb 2026), read 13 Oct 2026Wise help, what if I spend money in a currency I do not have in my account, read 13 Oct 2026Wise help, what are the Wise card fees, read 13 Oct 2026Wise, card fees for Singapore, with its calculator (page undated), read 14 Oct 2026MAS Financial Institutions Directory, Wise Asia-Pacific Pte. Ltd., read 14 Oct 2026Revolut Singapore, personal fees (Standard plan, undated page), read 15 Oct 2026Revolut Singapore help, problems with a refund, read 15 Oct 2026Revolut UK blog, using Revolut abroad (16 Jan 2026), on weekday and weekend rates, read 15 Oct 2026Revolut Singapore, cardholder terms (undated page), read 15 Oct 2026Revolut Singapore help, what currency will I be charged in, read 15 Oct 2026Revolut Singapore help, fees for card payments in a foreign currency, read 15 Oct 2026Revolut Singapore help, what exchange rates does Revolut offer, read 15 Oct 2026Revolut Singapore help, what currencies are supported for spending, read 15 Oct 2026Revolut Japan blog, how to exchange currencies with Revolut (22 Apr 2025), read 15 Oct 2026YouTrip help, why a petrol payment was deducted from the SGD wallet, read 13 Oct 2026YouTrip help, why the exchange rate and amount for SmartExchange can change, read 14 Oct 2026YouTrip Australia, product disclosure statement v1.1 (5 Nov 2025), a different entity, read 14 Oct 2026YouTrip help, why is my payment charged in a different currency, read 14 Oct 2026YouTrip help, why the original transaction amount changed from when I first split it, read 14 Oct 2026Wise help, my Wise card transaction is still pending, read 13 Oct 2026Wise help, Wise cards in Brazil, read 14 Oct 2026Wise UK blog, business card cashback (on how Wise earns from card use), read 14 Oct 2026Visa Core Rules and Visa Product and Service Rules, public edition (18 Apr 2026), sections 1.4.3.2, 1.4.4.5, 4.19, 5.8.9, 5.9.2.3 and 11.4.2, read 13 Oct 2026Visa, exchange rate calculator and note on which rate applies (US page, saved copy), read 14 Oct 2026Mastercard, currency converter and note on which rate applies (Singapore), read 14 Oct 2026Mastercard, Dynamic Currency Conversion Performance Guide, merchant version (2025), sections 2.1, 2.5.3 and 2.6, read 14 Oct 2026YouTrip help, why is my payment pending, read 15 Oct 2026YouTrip help, what to do if a refund is not reflected, read 14 Oct 2026Wise help, how can I receive money to my Wise card (includes refunds), read 15 Oct 2026YouTrip Singapore blog, wholesale exchange rates (12 wallet currencies, other currencies, 0.1 to 0.4 percent), read 17 Oct 2026

How to get the best rate

Four choices change what a tap costs, and all four are yours to make.

  1. Before you travel

    Check fees before picking a card

    A bank card adds 3.25% in total. Multi-currency cards charge 1% or less.

  2. Before you travel

    Choose when the rate is fixed

    Exchange to the local currency ahead and the rate is locked. Nothing converts at the tap.

  3. At the shop

    Pay in the local currency

    Decline the offer to pay in your home currency. The shop sets that rate, and bank cards add fees.

  4. At the ATM

    Take cash out less often

    Flat fees apply per withdrawal, so take out less often. Use any free allowance first.

Frequently asked questions

Why does a card charge differ from the rate on Google?

Flows A to F

Google shows the mid-market rate, and a card rarely pays that. It uses its own rate, adds a fee and may fix the rate on another day.

Details

Google shows a mid-market rate, while Visa's rules say its rate is set from a range of wholesale rates and need not be one it executed. A fee comes on top. DBS charges 1.00 percent from the scheme and 2.25 percent from the bank on the SGD amount of a credit card payment, and Standard Chartered shows 1 percent plus 2.5 percent. Wise states the mid-market rate plus a conversion fee, YouTrip states wholesale rates with no fee, and Revolut states its own rate with a spread. The rate is also fixed on a particular day.

Visa and Mastercard say the rate available at authorisation is used for clearing, with the rate at processing as the fallback. Some guides say otherwise. Wise's US blog says the rate is the one live on the day a purchase is processed, and its Canada blog says Mastercard usually applies the rate on the settlement date. Both blogs describe bank cards and not Wise's own conversion, and the two scheme pages agree with the rulebooks. Revolut says the rate shown at the payment is the one used for settlement, with a minor variation. A shop that converts through DCC sets its own rate and date.

What is dynamic currency conversion?

Flow B

It is the offer, at a terminal or ATM, to charge you in your own currency. The shop's bank or a DCC provider sets that rate, not Visa or Mastercard.

  • Who sets the rate The acquirer or its DCC provider, with its own margin. Mastercard says its rates do not apply.
  • What the shop must do Visa requires the shop to say the offer is optional, get express agreement and show the rate and margin on the receipt.
  • How to avoid it Pick the local currency. Wise and YouTrip both say so.
  • Not stated Whether YouTrip, Wise or Revolut cards are barred from DCC, and how often terminals offer it.
Details

It is the offer, at a terminal or ATM, to charge the card in the cardholder's own currency. The shop's acquirer or its DCC provider sets the rate and not the card scheme. Mastercard says DCC is not its product and its rates do not apply when the retailer converts. Visa requires the merchant to say the offer is optional, to get express agreement and to show the rate and any margin over a wholesale rate on the receipt.

Choosing the local currency avoids it. Wise's terms say to pick the local currency for its rate to apply, and YouTrip's help page says a terminal or ATM may offer the choice. Visa's rules and Mastercard's guide both bar DCC on certain multi-currency and travel prepaid cards, and no source read says whether YouTrip, Wise or Revolut cards are among them. Nor does any source read say how often terminals offer it.

Do bank debit and credit cards work the same way overseas?

Flows A to D

Yes, where the card carries Visa or Mastercard, and the fees take the same shape. They differ in how the money leaves and in what a DCC payment costs.

Details

Yes, where the card carries Visa or Mastercard. A debit card also has to be enabled for overseas use first, DBS says, and OCBC says its Visa debit card works for shopping online and overseas. The conversion fees take the same shape. DBS's guide gives one table for both, 1.00 percent from the scheme plus 2.25 percent from the bank, 3.25 percent in total, and OCBC's debit fee schedule gives the same 1 percent and 2.25 percent split. UOB's debit agreement states 3.25 percent without a split. The fee is for payments made overseas or through overseas-based online merchants, and a payment in SGD at a Singapore merchant is not in the table. DBS's guide is undated, and the OCBC schedule dates its rates from 16 January 2019.

They differ in how the money leaves. DBS says a debit card purchase is paid for by directly deducting the amount from the bank account, so it comes out of the balance. A credit card charge goes on a statement and is paid by the due date, with interest from the transaction date if it is not paid in full. Neither DBS nor OCBC publishes how long a debit hold lasts before the merchant's claim posts, so the page does not say it clears the same day.

They differ on a DCC payment. DBS shows 2.80 percent in total on a debit card, with a 1.80 percent bank fee, and only the scheme's 1.00 percent on a credit card. OCBC and UOB also charge 2.8 percent on an SGD payment processed overseas on a debit card. A debit card linked to a multi-currency account can skip the conversion. DBS, OCBC and UOB each debit the foreign balance with no FX fee when it holds enough, and the JPY is bought earlier at the bank's own rate. Flow D shows it. Whether a debit card with no Visa or Mastercard mark works abroad is not stated on the pages read.

Why do banks add their own fee on top of the Visa or Mastercard rate?

Flows A and C

Banks do not say. DBS and OCBC charge 2.25 percent on top of the 1 percent from Visa or Mastercard, and UOB states only 3.25 percent in total.

  • What is known DBS calls it an administrative fee, and UOB gives no split. The conversion itself is Visa's or Mastercard's, not the bank's.
  • How it varies By bank, with 2.5 percent at Standard Chartered, by product, and some cards waive it.
  • How it moved Banks raised it through 2018 and 2019, to 3.25 percent in total at DBS and OCBC.
  • Who sets it Visa and Mastercard leave it to the bank, which must disclose it.
Details

Banks do not say. DBS calls its 2.25 percent an administrative fee and gives no breakdown, and no page from MAS, a bank or a banking association read here gives a cost for it. MAS's 2015 letter describes only the card companies' international fee, between 0.8 and 1 percent. In the flow the scheme converts at authorisation and the issuer holds an SGD amount, so the conversion itself is not the bank's.

What the pages do show is how the fee behaves. It differs by bank for the same 1 percent from the scheme, 2.25 percent at DBS and OCBC and 2.5 percent at Standard Chartered. It differs by product, since DBS charges no bank fee on a credit card DCC payment and 1.80 percent on a debit card one. Some cards waive it, as UOB's EVOL card does. And it has moved. The MileLion's list records banks raising their total fee through 2018 and 2019, DBS from 2.8 to 3 percent in January 2019 and to 3.25 percent that November, and OCBC from 2.8 to 3 percent in March 2019 and to 3.25 percent that December. A fee that rose at most banks within two years, with no change in the service stated, is easier to read as a price than as a cost recovery, though no bank says how it sets it.

The schemes leave it to the issuer. Visa's rules let an issuer add an optional issuer fee of its own to Visa's rate and require the issuer to disclose it, and Mastercard's rules require an issuer to disclose any cross-border or currency conversion charge it passes on. The scheme's own part is 1 percent at each bank that splits it out.

What extra charges can an overseas ATM add?

Flows A to F

The ATM owner can add its own fee on top of your card's, and the machine can offer to charge you in SGD.

  • Three charges Your card's fee, the ATM owner's fee and the conversion.
  • The ATM owner YouTrip and Revolut both say the bank running the ATM may add its own fee.
  • DCC at the ATM The machine can offer it. Mastercard says the rate must be shown first. Pick the local currency.
  • Not stated What ATM owners in Japan charge.
Details

A withdrawal can carry three charges, the card issuer's, the ATM operator's and the conversion. YouTrip and Revolut both say the bank operating the ATM may add its own fee, and no page read gives what ATM owners in Japan charge.

Bank cards charge more. DBS's debit card page adds SGD 7 per overseas withdrawal to the conversion fees, and OCBC charges 3 percent of the amount, between SGD 5 and SGD 20, with nothing at OCBC's own ATMs overseas, and UOB's debit agreement adds a 2.5 percent fee plus SGD 5. On a credit card a withdrawal is a cash advance, and DBS lists 8 percent with a SGD 15 minimum, plus interest from the day of withdrawal.

An ATM can also offer DCC. Mastercard's guide covers ATM owners, says the cardholder must be told of the right to choose and shown the rate before choosing, and lists an ATM that offers only accept or cancel as automatic DCC, which its standards do not permit. Visa's rules put the same optional and express agreement requirements on ATM acquirers. Choosing the local currency avoids it.

How do multi-currency cards convert, and at what rate?

Flows E and F

They hold balances in advance and convert at their own rate. A spend from a balance that holds enough is not converted at the tap.

Details

On YouTrip, the card draws on wallets topped up in advance. YouTrip says there is no fee for exchange or overseas payments and that it uses wholesale rates. If the wallet for the shop's currency holds enough, the rate is locked when the cardholder exchanges or makes a purchase. If it is short, SmartExchange converts from the SGD wallet first, at its wholesale rate with no fee or markup.

For a currency outside its 12 wallets, the SGD wallet is charged and the rate shown at the tap is an indicative wholesale rate from Mastercard. The final rate is confirmed when the merchant completes the payment, usually in 1 to 2 days and up to 8. YouTrip says it earns a small commission from the merchant through Mastercard.

On Wise, Wise says the card spends at the mid-market rate with no markup, plus a conversion fee. Spending a currency already held is free and the payment is made in that currency. Its Singapore calculator showed a fee of SGD 1.98 on SGD 1,000 converted to JPY, and the fee page is undated.

An online seller can still add its own conversion fee, Wise says, and the schemes say their rates do not apply where the seller converts. When Wise prices the conversion, at authorisation or at clearing, is not stated. A refund in a supported currency is credited in that currency, so a JPY refund comes back as JPY.

On Revolut, Revolut says its rate is variable, set from market data from independent sources, and has a buy and sell spread of unstated size. The card pays from the currency of the purchase first, then SGD, then the active currency with the highest balance, and never combines currencies. A purchase that needs an exchange is priced at the payment, and Revolut says the rate shown at the payment is the one used for settlement, with a minor variation.

On a weekday the exchange costs nothing within a monthly allowance, SGD 5,000 on the Standard plan, then 1 percent. A weekend exchange costs 1 percent on the Standard plan, and Revolut says currency markets are closed at weekends. A weekend payment from a balance exchanged on a weekday carries no weekend fee. Its terms call the card a Visa or Mastercard debit card. A currency outside its supported list is not supported.

Keep exploring

Prying Debit vs credit card in Singapore: What you pay, what shops pay Prying Sending money overseas from Singapore: Banks, Wise, PayNow and QR payments Prying Why can’t every app scan every QR code? Singapore’s PayNow vs NETS QR

All interactive pieces